Not literally a power plant. But increasingly an energy campus that generates, consumes, stores, and manages power within one operating environment, alongside the compute it was built to house.
For much of conventional building automation practice, the electrical meter has functioned as an operational boundary: power arrives, and the building manages what happens downstream. That boundary has never been absolute. Microgrids, on-site generation, and two-way utility communication have been part of this industry’s own conversation for well over a decade. What is changing now is the scale and the speed. Grid interconnection queues have stretched long enough that developers are building substantial on-site generation as a primary power strategy rather than a backup plan, and grid operators are actively working out how much flexibility they can ask data centers for in return for a faster connection. Both trends push the control system’s job outward, into territory that has mostly belonged to utilities and power engineers until now.
That is a genuinely new scope for this industry, and it is arriving faster than most controls organizations have planned for.
The question is no longer whether building automation can optimize HVAC. It is whether it can participate in coordinating generation, cooling, electrical distribution, and IT workloads without becoming the system ultimately responsible for any one of them.
For much of conventional Building Automation practice, the electrical meter has functioned as an operational boundary: power arrives, and the building manages what happens downstream. Power comes in; the building manages what happens after that point. AI data centers are erasing that boundary. Grid interconnection queues have stretched so long that developers are building their own power plants on site, and grid operators are starting to ask those same data centers to throttle their own compute load during moments of grid stress. Both trends push the control system’s job outward, past the meter, into territory that used to belong to utilities alone.
That is a genuinely new scope for this industry, and it is arriving faster than most controls organizations have planned for.
The Boundary Is Moving
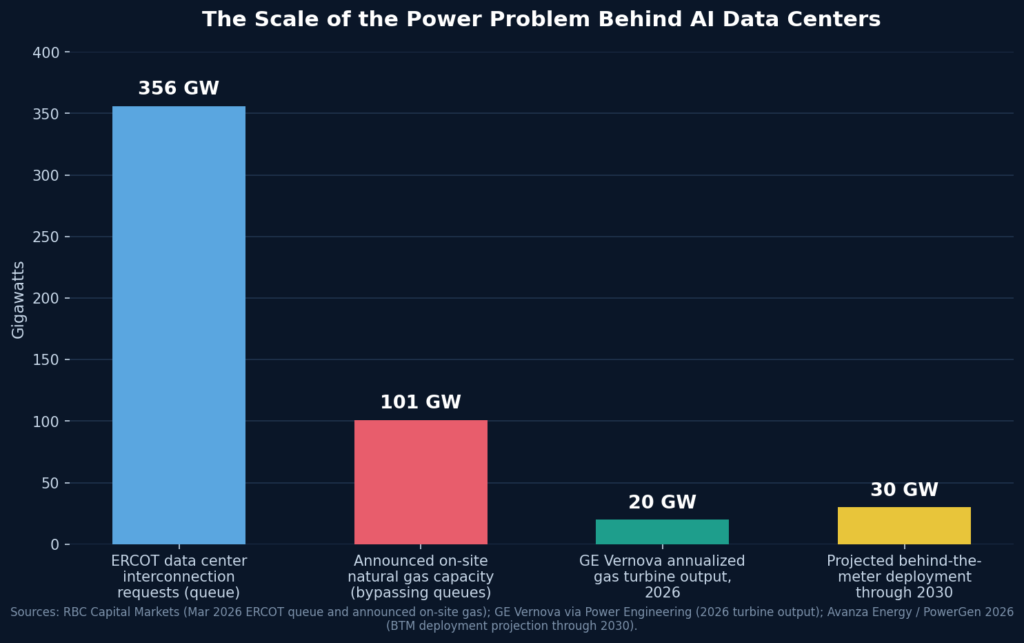
As of March 2026, RBC Capital Markets reported that ERCOT had received approximately 356 gigawatts of data center interconnection requests. That figure specifically represents requests in the queue, not built, financed, or contracted capacity, and it is worth treating as directional rather than precise. Other trackers following the same queue reported lower totals earlier in the year, in the 226 to 239 gigawatt range as of late 2025 and into 2026, reflecting how quickly the numbers are moving and how differently various sources define what counts as an active request. What every source agrees on is the direction: the queue has grown several times over in roughly a year, and grid planners themselves acknowledge only a fraction of it will ever be built.
Interconnection timelines across constrained U.S. markets commonly run three to seven years, depending on the region and how congested the local transmission system already is. AI infrastructure investment is not waiting that long. Developers have responded by announcing an estimated 101 gigawatts of on-site natural gas generation capacity, according to RBC, though a meaningful share of that is still speculative. RBC notes that just over 57 gigawatts already has publicly disclosed equipment orders behind it, and about 7 gigawatts is under construction, so the announced total and the committed total are not the same number. Turbine manufacturers are scaling to meet the committed portion regardless. GE Vernova is targeting 20 gigawatts of annualized gas turbine output in 2026, with further growth planned by 2028. Behind-the-meter power, once treated mainly as backup for outages, is becoming a primary power strategy for new AI facilities, with 25 to 35 gigawatts of behind-the-meter deployment projected through 2030, according to Avanza Energy’s analysis of the same buildout.
That is no longer only a utility-planning problem. It becomes a cross-domain coordination problem spanning controls, operations, and power engineering. A data center running its own turbines, switchgear, and thermal storage needs those systems coordinated with cooling and IT load in real time. That does not mean building automation should absorb the safety-critical functions of generation and grid protection, which will continue to sit with dedicated PLC, SCADA, protection, and microgrid-control systems for good reason. It means building automation has to become a trusted participant in a broader supervisory architecture, exchanging operational data and coordinating cooling and demand without pretending to replace the systems built specifically to keep power safe.
Sources
RBC Capital Markets, “Natural gas powers the data center boom,” May 2026
Build, “Behind-the-Meter Power for Data Centers: Why Gas Turbines Are Back in the Stack,” May 2026
Interconnection Queue Tracker, ERCOT large-load queue data, updated July 2026
Utility Dive, “ERCOT’s large load queue jumped almost 300% last year,” January 2026
Curtailment as the Price of a Faster Connection
Grid operators are working through a different kind of trade with large loads. On October 23, 2025, the U.S. Secretary of Energy directed the Federal Energy Regulatory Commission to initiate a rulemaking on how large loads interconnect to the transmission system. Rather than issue a single national rule, FERC responded on June 18, 2026, with six tailored show cause orders under Section 206 of the Federal Power Act, one to each of the country’s regional grid operators, PJM, MISO, SPP, CAISO, ISO-NE, and NYISO, directing each to justify or reform its own tariff provisions for how data centers and other large loads connect and pay for service. FERC defined large loads as those with peak demand above 50 megawatts connecting at transmission voltages above 69 kV. Among the changes FERC asked grid operators to consider is new transmission service specifically for large loads capable of curtailing, shaping, or otherwise managing their own demand in exchange for faster or cheaper interconnection. This is a live, unsettled process, not a finished regulation. Generation adequacy reports from the grid operators were due in July 2026, and the tariff reform proceedings themselves remain open.
In practical terms, regulators and grid operators are beginning to treat curtailment capability as part of what makes a large load easier and faster to connect, not as a settled national mandate but as a direction several major markets are now moving in at once.
What that curtailment actually costs varies by facility. In conventional commercial demand response, temporary HVAC curtailment is often absorbed through comfort tolerances or thermal storage without much consequence. In a hospital, laboratory, industrial site, or AI data center, curtailing a cooling plant is not always a comfort question; it can be a safety or process question, and curtailing AI training or inference load directly can affect service continuity and revenue. For contracted AI workloads, that is not just lost revenue; it can mean violating latency and uptime service-level agreements with customers who assumed uninterrupted compute. Coordinating that decision automatically, in real time, against cooling capacity, thermal storage, and whatever on-site generation is available at that moment, is a materially harder control problem than traditional demand response.
This is not a new concept to this publication. AutomatedBuildings.com was writing about buildings bidding for power inside microgrids as far back as 2010, and by 2013 was already covering the need for two-way communication between buildings and utilities for demand response and on-site generation. What is new in 2026 is the scale, the speed, and the fact that federal regulators are now actively rewriting interconnection tariffs with curtailment-capable load explicitly in mind.
Sources
Akin Gump, “FERC Issues Landmark Show Cause Orders on Large Load Interconnection,” June 2026
RMI, “Understanding FERC’s Large Load Orders,” July 2026
Utility Dive, “What data center developers need to know about FERC’s large load directives,” June 2026
AutomatedBuildings.com, “Microgrids and Smart Energy,” April 2010
AutomatedBuildings.com, “Defining a Smart Building: Part Four,” November 2013
The Integration Problem
This is the open question worth sitting with. Historically, generation belonged to power engineers and utilities, and building automation stopped at the meter. A data center running its own turbines, batteries, and grid-curtailment logic alongside its cooling plant needs those domains talking to each other in real time, spanning BMS, EPMS, SCADA, DCIM, and IT workload orchestration, systems that were mostly never designed to share a common operating picture.
Many of the enabling technologies already exist: protocol-neutral edge platforms, long-distance building networks, power and data transmission, microgrid controls, and cross-domain data normalization. What has not yet emerged is a broadly accepted, vendor-neutral architecture defining how those layers should interoperate and where operational accountability sits. This is also not a completely blank page. NIST’s National Cybersecurity Center of Excellence has already published reference architecture work, NIST SP 1800-32, demonstrating gateways, command registers, and audit trails for secure communication between utility systems and microgrid distributed energy resources. That work was built for the DER cybersecurity problem specifically, not for coordinating a data center’s cooling, compute, and generation as one system, but it shows the underlying pattern, gateways, command registers, auditable exchanges, already has a working precedent elsewhere in the industry.
The industry has not yet converged on a broadly accepted architecture, division of responsibility, or integration layer for this specific problem. No single system layer has clearly won the right to coordinate the whole environment.
That naturally raises the question of who takes that role. The eventual coordination layer may not belong to any one existing system. It could emerge as a vendor-neutral supervisory platform exchanging trusted operational data across BMS, EPMS, SCADA, DCIM, utility interfaces, and AI workload orchestration. Whether that layer evolves from today’s building automation platforms, microgrid controllers, or something entirely new remains an open architectural question.
A Third Thread Worth Watching: Waste Heat as Revenue
One more piece belongs in this picture. Data center operators using liquid cooling are increasingly looking at captured waste heat as a saleable output, not just a cooling burden, particularly in colder climates with existing or planned district-energy infrastructure. ASHRAE’s data center guidance already treats waste-heat and district-energy integration as a design consideration, not a novelty. Exact revenue impact varies by climate, cooling architecture, and the availability of a nearby heat customer, so specific savings figures should be treated with caution until tied to a named project and methodology.
Combine that possibility with on-site generation and curtailment logic, and the modern AI data center starts to resemble a small, largely self-contained energy system that happens to also run servers, generating power, consuming it, shedding it, and potentially reselling its own waste heat, inside one operating boundary.
What Building Automation Must Now Prove
Building automation has spent decades learning to manage complexity inside a single building. Coordinating an energy campus asks for a different kind of proof. Building automation now has to demonstrate five capabilities:
- Interoperability across BMS, EPMS, SCADA, DCIM, and generation control systems that were never designed to share data.
- Resilience when a curtailment signal, a generation fault, and a cooling load spike happen at the same time.
- Cybersecurity models that treat the boundary between IT load and on-site power generation as a single attack surface rather than two separate ones.
- Trustworthy operational data, strong enough that a control decision can be trusted to reflect the actual current state of the system, not a stale snapshot of it.
- Whole-system commissioning capable of verifying all of the above before a facility ever goes live, not discovering the gaps afterward.
None of that is hypothetical. It is the practical version of the architecture question the rest of this piece has been circling.
The Open Market Question
Standards such as BACnet Secure Connect establish who issued a command and whether the communication carrying it was protected. They do not, by themselves, prove that the underlying data was accurate, that the operating condition that justified the command still exists, or that executing it is safe. As data centers turn their electrical boundary into a live, continuously negotiated control surface, generation, curtailment, cooling, and compute all coordinating in real time, that distinction stops being theoretical. The industry will need stronger approaches to state verification, command assurance, and accountable autonomous control, not just stronger identity and access management.
This is a major opportunity for building automation, but not because building automation should become a power-plant control system. The opportunity is to become the trusted integration and verification layer between power, cooling, compute, and building operations. Whether the industry can prove it is ready for that role remains an open question.
Sources and Further Reading
RBC Capital Markets, “Natural gas powers the data center boom,” May 2026
Build, “Behind-the-Meter Power for Data Centers: Why Gas Turbines Are Back in the Stack,” May 2026
Interconnection Queue Tracker, ERCOT large-load queue data, updated July 2026
Akin Gump, “FERC Issues Landmark Show Cause Orders on Large Load Interconnection,” June 2026
RMI, “Understanding FERC’s Large Load Orders,” July 2026
NIST NCCoE, SP 1800-32, “Securing Distributed Energy Resources”
AutomatedBuildings.com, “Microgrids and Smart Energy,” April 2010
AutomatedBuildings.com, “Defining a Smart Building: Part Four,” November 2013
More From AutomatedBuildings.com
A Trust Matrix for the Autonomous Building, a framework for how trust shifts as buildings move from human-operated to agent-operated
Buildings Are Becoming Intelligent Before They Are Admissible, Greggory Don Butler on why authorized action and admissible action are not the same thing
The Governance Exchange Has Arrived, the TA-14 framework this piece’s closing section builds on